The polyurethane (PU) foam industry rarely finds itself at the center of geopolitical discussions. Yet the ongoing conflict involving Iran and the disruption of trade flows through the Strait of Hormuz have demonstrated how closely modern manufacturing remains tied to global energy and petrochemical markets. India’s PU foam sector, the consequences are being felt not through direct trade with Iran, but through a global supply chain that depends heavily on energy, feedstocks and logistics networks linked to the Middle East. Polyurethane foam is one of the most widely used industrial materials in the modern economy. It forms the comfort layers of mattresses, cushions furniture, insulates buildings and refrigeration units, and provides seating solutions for automobiles, buses and aircraft. Despite its ubiquitous presence, few consumers realise that every mattress, sofa cushion or insulated panel begins its journey in the global petrochemical industry.
The Strait of Hormuz remains one of the world’s most strategically important maritime corridors. A significant share of global crude oil and liquefied natural gas (LNG) exports passes through this narrow waterway connecting the Persian Gulf with international markets. Any disruption to this route immediately raises concerns about energy supplies, shipping reliability and commodity prices. While the headlines often focus on crude oil, the consequences extend much further, affecting industries that depend on petrochemical feedstocks, including polyurethane.
India’s PU foam industry has grown steadily over the past two decades alongside the expansion of the organised mattress, furniture, automotive and construction sectors. Rising urbanisation, increasing disposable incomes, growing awareness of sleep health and the premiumisation of consumer products have all contributed to rising demand for polyurethane-based solutions. Flexible PU foam has become a critical component of modern mattresses and upholstered furniture, while rigid polyurethane foam plays a growing role in insulation, cold-chain infrastructure and energy-efficient construction.
Yet beneath this growth story lies an important structural reality. While India possesses a substantial downstream manufacturing base, the industry continues to depend heavily on imported polyurethane feedstocks and specialized chemical intermediates. The importance of this dependence was underscored in April 2026 when the Government of India temporarily removed customs duties on key polyurethane feedstocks, including MDI (Methylene Diphenyl Diisocyanate), TDI (Toluene Diisocyanate) and polyether polyols, in an effort to ease supply pressures for downstream industries. The decision highlighted an often-overlooked fact: although foam is manufactured domestically, many of the critical ingredients required to produce it originate overseas.
India’s principal sources of polyurethane materials and feedstocks include China, Singapore, Germany, the Netherlands and South Korea. These countries collectively account for a substantial share of India’s imports of polyurethane chemicals and related materials. At first glance, this may appear to insulate Indian manufacturers from developments in the Gulf. After all, India is not importing significant quantities of polyurethane feedstocks directly from Iran. The reality, however, is far more complex. The war has highly affected the supply chain and logistics, which is reflected in the polyurethane foam industry as well, said Advocate Sudhir Babu, India’s Honorary Trade Commissioner for the United Arab Emirates (UAE) under the India-GCC Trade Council.
“In the present scenario, the production and transportation of PU have considerably impacted, and even if the production is there, the logistics is an issue and Indian manufacturers would definitely face the problems of dwindling supply of raw materials,” he said, pointing to the issue of logistics affecting Indian manufacturers. Moreover, those who are into the export of mattress here will also face the issues in export. Further, in places like UAE, even the local manufacturers are affected because of the raw material issue. “Normally, a smalltime manufacturer of mattress will have hardly six months backup and if they are unable to manufacture and sell products properly, it would definitely affect their survival. I am sure this is what Indian manufacturers, especially the smalltimers, face.”
As we all know, the polyurethane industry is part of a deeply interconnected global petrochemical ecosystem. The chemicals used to manufacture polyurethane foam, primarily polyols and isocyanates, are derived from hydrocarbon-based feedstocks. Their production requires crude oil derivatives, natural gas liquids, naphtha, propane and a range of petrochemical intermediates. Equally important, the manufacturing process itself is highly energy-intensive, requiring substantial amounts of heat, power and steam. This means that the cost of producing polyurethane chemicals is influenced not only by chemical demand but also by developments in global energy markets. Chemical manufacturers in China, South Korea, Singapore and Europe may supply India’s polyurethane industry, but they themselves operate within a supply network that depends on energy resources and feedstocks whose prices are shaped by global markets. Many rely on imported hydrocarbons. Others depend on LNG to power manufacturing facilities. Consequently, when tensions in the Gulf disrupt energy markets, the effects are transmitted across the entire petrochemical value chain.
industry, but they themselves operate within a supply network that depends on energy resources and feedstocks whose prices are shaped by global markets. Many rely on imported hydrocarbons. Others depend on LNG to power manufacturing facilities. Consequently, when tensions in the Gulf disrupt energy markets, the effects are transmitted across the entire petrochemical value chain.
The Strait of Hormuz plays a critical role in this process. The waterway handles a significant portion of global crude oil and LNG exports, making it one of the most important arteries of international trade. Disruptions create uncertainty regarding energy availability and pricing, affecting manufacturers far beyond the Middle East. This is why the impact of the Iran conflict extends well beyond countries directly involved in the region. Rising energy costs increase the production expenses of chemical manufacturers around the world. Higher feedstock prices place additional pressure on margins. Freight costs and insurance premiums add another layer of expense. Ultimately, these costs are passed along the supply chain.
The volatility has also sparked debate within the industry regarding the extent to which raw-material inflation is being reflected in downstream pricing. Rakshith Siddalingappa, a Bengaluru-based material sourcer and wholesaler specialising in polyurethane foam sheets and furnishings, recently questioned the scale of recent price increases in a LinkedIn post. Referring to the sharp rise in TDI prices, he wrote “While TDI is a major cost driver, passing down a 45% increase to distributors and ultimately the end consumer feels entirely disproportionate.”
The importance of these raw materials is evident in corporate risk disclosures. In its annual report, Sheela Foam, maker of the Sleepwell brand, identifies TDI and polyols among its principal manufacturing inputs and acknowledges the risks arising from volatility in their prices. The company notes that fluctuations in the cost of these materials can directly affect production economics, prompting risk-management measures including long-term purchase arrangements and periodic product price revisions. Significantly, the company also points to geopolitical developments in the Middle East and disruptions around the Strait of Hormuz as factors contributing to longer transit times, elevated freight costs and uncertainty in input prices, even when overall supply conditions remain relatively adequate.
TDI, one of the principal raw materials used in manufacturing flexible polyurethane foam, has witnessed successive price increases since late 2025. Major producers, including BASF, announced hikes ranging from US$200 to US$500 per metric tonne across Asian markets, citing higher raw-material, transportation and energy costs. These increases have added significant cost pressure on downstream foam manufacturers and, ultimately, the mattress industry. The impact can already be observed across multiple polymer markets. Polyester yarn producers in India have reported rising feedstock costs linked to disruptions in petroleum-derived raw materials. Similar concerns are emerging within the polyurethane sector as chemical producers, distributors and manufacturers adapt to a more volatile operating environment.
Rising costs and procurement challenges
For India’s PU foam industry, the immediate concern is not necessarily the availability of raw materials but the cost and predictability of obtaining them. Raw materials account for a significant share of foam manufacturing costs. Polyols, MDI and TDI are specialised chemical inputs that cannot be substituted easily or sourced from alternative suppliers without careful qualification and testing. Manufacturers therefore depend heavily on reliable supply chains and consistent product specifications. As energy markets fluctuate and freight rates rise, procurement teams face a difficult balancing act. Buying too little inventory increases the risk of production interruptions. Buying too much inventory exposes companies to elevated working-capital requirements and the possibility of future price corrections.
Even when supplies remain available, replacement costs become increasingly uncertain. Freight rates have risen on several trade routes, while shipping schedules have become less predictable. Chemical importers report longer planning cycles and reduced visibility regarding future delivery timelines. This uncertainty affects the entire value chain. Foam manufacturers must decide whether to absorb higher costs or pass them on to customers. Mattress manufacturers must determine how much inflation the market can tolerate. Dealers and distributors face the challenge of maintaining sales momentum in an increasingly competitive environment.
The challenge is particularly significant because polyurethane markets do not operate in isolation. Rising costs for one component frequently coincide with increases in packaging materials, transportation expenses and energy consumption. As a result, manufacturers often experience inflationary pressure from multiple directions simultaneously. For companies operating on narrow margins, these pressures can become difficult to absorb over extended periods. And, among the sectors most exposed to polyurethane volatility is the mattress industry.
Flexible polyurethane foam remains one of the most widely used comfort materials in mattresses across all price categories. Whether in conventional foam mattresses, memory foam products or hybrid sleep systems, polyurethane continues to play a central role in comfort, support and durability. For the mattress industry, polyurethane is far more than a commodity input. The quality, density and formulation of foam largely determine a mattress’s comfort, support and durability. Whether it is conventional PU foam, high-resilience foam or memory foam, manufacturers depend on a steady flow of specialised chemicals to maintain product consistency. This makes the sector particularly sensitive to disruptions in raw-material markets. Even modest increases in feedstock costs can affect margins, especially in a highly competitive market where manufacturers must balance dealer incentives, promotional campaigns and consumer price expectations. As India’s organised mattress sector continues to expand, ensuring stable access to polyurethane raw materials is becoming as important as product innovation and brand differentiation.
The growth of India’s organised mattress industry has further increased the importance of stable polyurethane supplies. Over the past decade, consumers have become increasingly aware of sleep quality and ergonomic support. Premium mattress categories have expanded rapidly, while e-commerce has broadened market access across the country. This transformation has created significant opportunities for manufacturers. It has also increased their exposure to fluctuations in foam costs. Unlike commodity industries where prices can be adjusted rapidly, mattress manufacturers often operate within highly competitive retail environments. Dealer margins, institutional contracts, promotional campaigns and online pricing
Foam inflation often appears first in company margins rather than retail price tags. This affects small scale manufacturers more than the big players.
strategies frequently limit the ability to pass through cost increases immediately. As a result, foam inflation often appears first in company margins rather than retail price tags. Large manufacturers may possess greater bargaining power and diversified sourcing networks, enabling them to manage volatility more effectively. Smaller manufacturers, however, may have fewer procurement options and less flexibility when faced with sudden increases in raw-material costs.
For many industry participants, the current situation evokes memories of the pandemic-era supply-chain crisis. While the causes are different, the lessons are remarkably similar. Companies with diversified suppliers, stronger inventory planning and greater procurement flexibility tend to weather disruptions more successfully than those dependent on narrow sourcing arrangements. The significance of polyurethane extends far beyond the bedding industry.
Furniture manufacturers depend heavily on flexible polyurethane foam for seating applications. Sofas, recliners, office chairs and hospitality furniture all rely on foam to deliver comfort and durability. Cost increases therefore have direct implications for furniture production economics. The automotive sector represents another major consumer of polyurethane materials. Seats, headrests, armrests, acoustic insulation components and interior comfort systems frequently incorporate polyurethane-based products. As vehicle manufacturers continue to emphasise passenger comfort and weight reduction, polyurethane remains an important material within automotive design.
The footwear industry is similarly exposed. Polyurethane components are widely used in midsoles and cushioning systems, making the sector sensitive to fluctuations in chemical prices. Recent reports from manufacturing clusters have already highlighted concerns regarding rising costs for polyurethane-related inputs.
Construction and refrigeration industries also rely heavily on polyurethane chemistry. Rigid polyurethane foam is widely used in insulation systems, cold-storage facilities and refrigeration equipment because of its thermal efficiency. Any sustained increase in raw-material costs can therefore influence sectors linked to infrastructure, logistics and food preservation. This broad industrial footprint explains why developments affecting polyurethane feedstocks attract attention far beyond the chemical industry itself. The material sits at the intersection of multiple manufacturing sectors, making it a useful indicator of wider industrial trends.
Hence, if the immediate lesson of the Iran conflict concerns cost pressures, the longer-term lesson concerns India’s dependence on global polyurethane feedstocks and the need to reduce its exposure to external disruptions. For years, manufacturers across industries focused on maximising efficiency through lean inventories and just-in-time procurement systems. These strategies reduced working-capital requirements and improved operational performance during periods of stable global trade. Recent events have exposed their vulnerabilities.
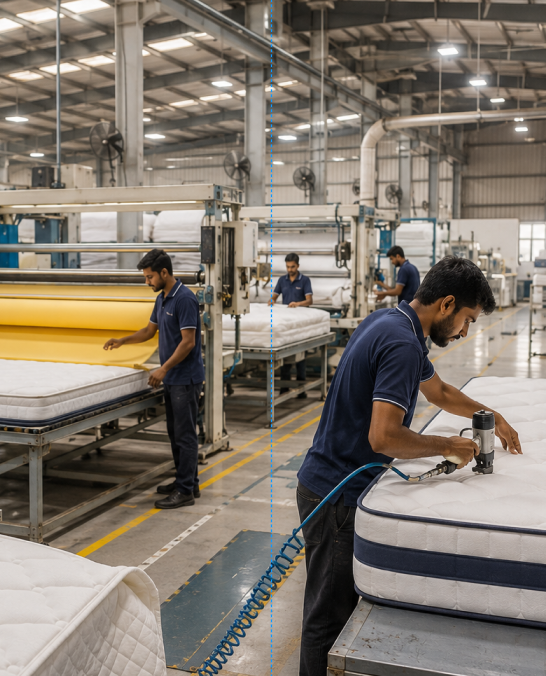
The pandemic demonstrated how quickly global supply chains could become disrupted. The current geopolitical tensions are reinforcing the same message: efficiency alone is no longer sufficient. Supply security and resilience are becoming equally important considerations.
Many companies are therefore reassessing procurement strategies. Diversifying supplier bases, increasing inventory buffers and strengthening relationships with distributors across multiple regions are increasingly viewed as prudent risk-management measures rather than unnecessary costs. The current environment is also renewing discussions about domestic chemical manufacturing capacity. While India has developed a substantial petrochemical sector, portions of the polyurethane value chain remain dependent on imported intermediates and specialised feedstocks.
Expanding domestic capabilities could improve long-term supply security and reduce exposure to external disruptions.
The Iran conflict will eventually subside, and global shipping networks may stabilise. Yet the broader lessons are likely to endure. The events of 2026 have demonstrated that the polyurethane industry is inseparable from the global networks of energy, chemicals and logistics that support modern manufacturing. For India’s PU foam industry, the challenge is no longer simply managing a temporary increase in raw-material costs. It is adapting to a world where geopolitical developments thousands of kilometres away can influence procurement decisions, production economics and competitive positioning. The conflict has not created India’s dependence on global polyurethane supply chains; it has exposed it. How the industry responds may well shape its resilience and competitiveness for years to come.
Conclusion
While Indian PU foam manufacturers do not import substantial quantities of feedstocks directly from Iran, they are heavily dependent on global energy and petrochemical markets. Polyurethane production relies on hydrocarbon-based inputs (like crude oil derivatives, natural gas liquids, and naphtha) and energy-intensive manufacturing processes. Consequently, geopolitical disruptions in the Strait of Hormuz immediately trigger volatility in global energy prices, freight rates, and feedstock costs across primary supplying nations such as China, Singapore, Germany, the Netherlands, and South Korea.
The disruption manifests not as an absolute absence of raw materials, but through steep price inflation, unpredictable lead times, and logistical bottlenecks. Key raw material inputs such as TDI, MDI, and polyester polyols have seen sharp price hikes. This directly strains the profit margins of downstream industries. These include mattress & bedding which are particularly vulnerable due to competitive retail environments that limit the immediate pass-through of cost increases to consumers, Automotive & furniture industry which are facing rising production costs for seating, cushioning, and acoustic components.
This crisis exposes a major disparity between large corporate players and smaller industry participants. While larger companies manage risks using long-term purchase agreements and price adjustments, smaller manufacturers typically operate with limited inventory backups (often less than six months) and lack procurement flexibility. Prolonged cost pressures and supply delays threaten the very survival of these small-time manufacturers. Recognizing the severity of these pressures, the Indian government temporarily eliminated customs duties on key PU feedstocks (MDI, TDI, and polyols) in April 2026 to ease domestic supply constraints. Concurrently, corporate risk disclosures highlight a strategic shift toward active inventory hedging and periodic price revisions.
The conflict serves as a critical wake-up call for India’s manufacturing sector. Lean, just-in-time procurement strategies once prioritized for efficiency have proven highly fragile under geopolitical strain. To build long-term competitiveness and resilience, India’s PU foam industry must move away from narrow supply channels and establish broader global supplier bases. Maintain larger raw- material stocks to absorb transit delays and price spikes. Invest in domestic chemical manufacturing infrastructure to produce specialized intermediates locally, thereby reducing structural reliance on foreign feedstocks. The Iran conflict has not created India’s dependence on global polyurethane supply chains; it has laid it bare. Long-term stability will depend on shifting from pure cost-efficiency to deliberate supply-chain resilience and domestic capacity building.
CEO Corner
V. Balaji, Director Marketing, Repose Mattress
Global conflicts are no longer distant events for the Indian PU foam industry – they directly influence raw material costs, supply and margins. In an interconnected world, geopolitical uncertainty has become a business variable we can no longer ignore.
Industry in 5 Minutes
- India remains heavily dependent on imports for critical PU raw materials like TDI and MDI. Geopolitical conflicts in key production regions or shipping lanes immediately create severe supply squeezes. Implement high-efficiency rebonded foam processing lines to recycle in-house foam trimmings and post-industrial waste, lowering the reliance on virgin PU chemical pours.
- Large foam manufacturers and chemical system houses can maintain rolling 60–90 day buffer stocks of critical petrochemical inputs and enter index-linked, long-term supply contracts to absorb short-term spot market price spikes.
- Maximize the use of high-compression vacuum roll-packing technology to optimize container volume usage, mitigating the cash-flow impact of soaring ocean and domestic freight costs.
- Foam suppliers and mattress manufacturers can move toward quarterly or flexible contract pricing linked to raw material benchmarks, preventing catastrophic margin erosion during sudden commodity spikes.